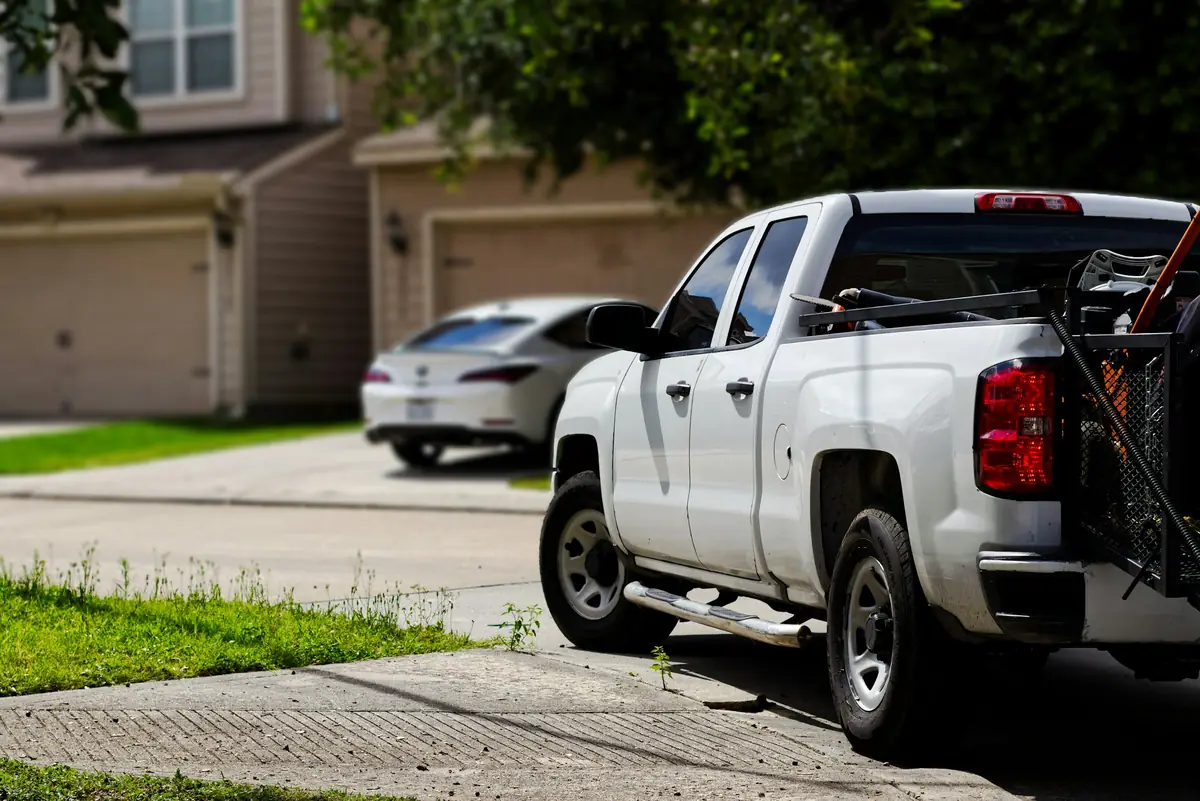
A work pickup needs the same policy structure as any business vehicle, with a few details that matter more.
Liability and the Trailer Behind the Truck
Liability covers injuries and property damage your driver causes, normally at the $1,000,000 combined single limit Tampa Bay general contractors request on certificates. Florida's baseline of $10,000 personal injury protection and $10,000 property damage liability applies to the truck as a registered vehicle (ss. 627.736, 324.022, Fla. Stat.).
Liability generally extends to a trailer being towed, which is the part owners get right by accident. What does not extend is physical damage on that trailer or the equipment on it, covered on our trailer and equipment insurance page.
Physical Damage on Trucks That Get Modified
Collision and comprehensive repair the truck itself, including theft, hail, flood and named-storm damage. Work trucks rarely stay stock: utility bodies, toolboxes, headache racks, lift kits, winches and ladder racks all add value that has to be declared.
Modifications also affect valuation after a total loss. A truck written at actual cash value is settled at depreciated market value, which usually does not account for a service body or a custom upfit unless it was disclosed and rated. Stated value is the better structure for heavily upfitted one-tons.
Employee-Owned Trucks on Your Job Sites
Crew members following the job in their own pickups create a non-owned auto exposure the moment they carry tools or drive between sites. That is covered by hired and non-owned auto insurance, not by the policy on the company trucks, and it is inexpensive to add.